

TD Bank (US)

- 33.83K Reviews
- 4.2
- Downloads
- 5,000,000+
Our take on TD Bank (US) from Appgk
Managing a bank account from a phone sounds simple until the moment you need to check a balance, move money, or confirm a transaction while you are away from a computer. TD Bank (US) is built around that everyday situation. I found it most useful as a mobile companion for routine banking, especially when I already had a dependable connection and wanted to complete a quick task without visiting a branch or opening a desktop browser.
This is a free finance app from TD Bank, N.A., aimed at an Everyone audience. It has been available since August 14, 2010, and its current release is 26.10.1.71 for devices running iOS or Android 12 and later. The app has an average rating of 4.2 from around 90 thousand ratings, with more than 5 million installs. Those figures suggest that it is a well-established option for TD customers, although popularity alone does not make it the right banking tool for every situation.
My main focus here is practical: how the app behaves when connectivity is strong, when mobile service is inconvenient, and when a banking task does not go exactly as planned. A finance app is judged differently from a game or social platform. A delayed screen, an interrupted transfer, or uncertainty about whether an action went through can create real stress. That makes the relationship between the app and your network connection especially important.
How TD Bank (US) handles banking on the move
Network-dependent moments are where the experience matters most
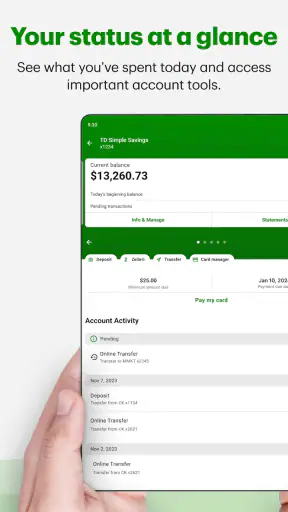
The app feels most natural when I use it for short, intentional sessions. I open it to review recent account activity, check whether a payment or deposit has appeared, or take care of a transaction that would otherwise require a laptop. These tasks depend on the app reaching TD’s services, so a stable connection is not just convenient; it is part of the basic experience.
Best Parts of TD Bank (US)
Things to Keep in Mind About TD Bank (US)
On a reliable home Wi-Fi network or a strong mobile signal, the process is straightforward. Screens load in a sensible order, and the app is better suited to quick checks than to long financial planning sessions. I would not treat it as a replacement for every banking conversation or every detailed document I might want to examine, but it does reduce the need to sit at a desk for ordinary account management.
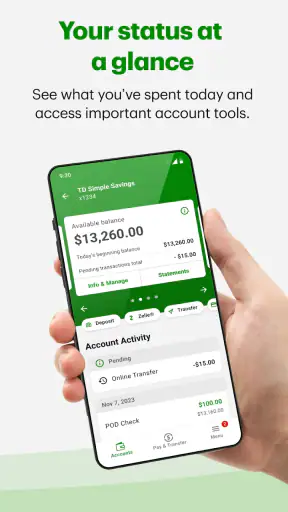
The important distinction is between information already displayed on screen and information that needs to be refreshed. A balance or transaction list can look available because the previous screen remains visible, but that does not necessarily mean it reflects the latest activity. When timing matters, I make sure the app has had a chance to connect before relying on what I see. This is a small habit, but it is particularly useful around scheduled payments, recent purchases, or expected deposits.
News and Features Related to TD Bank (US)

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
Connectivity also affects confidence. In a finance app, a loading delay is not merely annoying. I want to know whether a request is still being processed, whether the session has expired, or whether my connection has dropped. The app is most comfortable for actions where I can pause and verify the result. If I am in a place with unstable service, I prefer to postpone anything that could create uncertainty rather than repeatedly tapping the same control.
Mobile contexts reveal the app’s real strengths
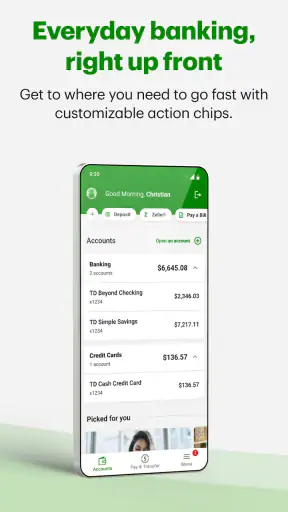
TD Bank (US) makes the most sense in the situations where a phone is already the device I have with me. Imagine leaving a store and wanting to confirm that a purchase has been recorded correctly. I can open the app, wait for the account information to refresh, and compare the recent activity with the receipt. That is faster than waiting until I get home, provided the connection is good enough to retrieve current information.
Don't want to read the full review?
Another useful scenario is checking an account before making a larger everyday decision, such as paying a bill or moving money between accounts. The phone gives me a quick view while I am away from my desk, but I still take a moment to confirm the destination and amount before submitting anything. The convenience is real, yet the small screen makes careful review more important than it would be on a desktop.
I also like the app for brief check-ins rather than leaving it open while I work through a complicated financial task. Short sessions reduce the chance of losing track of what I have already reviewed, and they make it easier to notice when the connection has changed from Wi-Fi to mobile data. If the app suddenly behaves differently, I know to check the network before assuming that my account or the application itself is at fault.
Screenshots
Travel is a more mixed case. A phone-based banking app can be reassuring when I need to check activity away from home, but unfamiliar networks can make me more cautious. I would avoid logging in through a questionable public connection and would not begin a time-sensitive transaction in a place where service repeatedly cuts out. The app is convenient in mobile contexts, but convenience should not replace basic security judgment.
What to do when a session fails or a request feels uncertain
The most important recovery habit is to avoid repeating an action immediately after a connection failure. If a screen freezes after I submit something, I first look for a confirmation, then check the relevant account activity after the app reconnects. Tapping again without checking can create confusion, particularly when the first request may have reached the bank even though the response did not return cleanly.
I treat a failed refresh differently from a failed transaction. If a balance page does not update, I can usually wait, reconnect, and try viewing it again. If I have just initiated a money movement or payment-related action, I slow down and verify the result before doing anything else. That distinction is one of the most useful ways to use a mobile banking app responsibly: not every error deserves the same response.
When the app behaves oddly, I work through the simplest causes first. I check whether other apps can reach the internet, switch between Wi-Fi and mobile data when appropriate, and reopen the banking session. I also make sure the device meets the stated minimum of iOS or Android 12, since compatibility matters more for a finance app than it might for a casual utility. Keeping the application current is sensible as well, especially when a problem appears after a device or operating-system change.
There is a trade-off here. A mobile app can be faster than a browser for familiar tasks, but a browser on a larger screen may be easier when I need to compare several details or recover from a confusing interruption. If a session becomes unclear, I prefer changing the context rather than forcing the phone to complete a task under poor conditions. That might mean waiting for a stronger connection or moving to a trusted computer, depending on what I need to verify.
Using the app without wasting mobile data
Banking apps are not usually the kind of software I leave running for entertainment, so my data use is naturally limited when I use TD Bank (US) deliberately. The practical approach is to open it for a specific purpose, allow the account information to load, complete the task, and close the session. Constantly refreshing a transaction list rarely adds useful information and can be frustrating on a weak mobile signal.
When I know I will be checking an account several times, I avoid doing so merely out of habit. I decide what I need to confirm first: a balance, a recent transaction, or the status of a particular action. This makes the session shorter and reduces unnecessary requests over mobile data. It also helps me distinguish a genuinely new update from a screen that simply has not been refreshed.
Wi-Fi is convenient, but I do not assume every available network is appropriate for banking. A trusted personal connection is preferable to an open network in a café, airport, or hotel. If I am unsure about the connection, I wait or use a more dependable mobile connection rather than prioritizing a few seconds of convenience. This is less about the app’s interface and more about fitting mobile banking into sensible habits.
There is another data-conscious benefit to being selective: fewer interruptions. In a crowded area, a phone may move between weak signals or struggle with congestion. Starting a transaction only when the connection is steady lowers the chance of an ambiguous result. I would rather spend a minute preparing the right conditions than spend several minutes trying to determine whether an action completed.
Where it compares well with usual banking alternatives
Compared with visiting a branch, the app is clearly more convenient for routine account checks and simple actions that do not require a conversation. It is available in the pocket, avoids travel, and fits naturally into moments when I already have my phone nearby. For existing TD customers, that makes it a practical first stop for everyday banking rather than a tool reserved for emergencies.
Compared with using a mobile browser, a dedicated app generally feels more focused. I do not have to begin by finding the bank’s website, and the experience is designed around a smaller screen. That said, a browser can still be preferable when I am working from a computer, need more room to inspect information, or want to keep several windows visible while organizing my finances.
Compared with independent budgeting apps, TD Bank (US) serves a different purpose. It is the direct banking companion for TD customers, not a neutral planning workspace that I would choose simply to combine accounts from many institutions. Someone who wants broad household budgeting across different banks may prefer a dedicated finance organizer. Someone who mainly needs access to TD banking while away from a desk will likely find the official app more relevant.
The same distinction applies to customer support. An app can help me handle routine actions, but it cannot replace every situation in which I need clarification, dispute assistance, or a detailed explanation. If the issue involves an unfamiliar transaction or a complicated account question, I would use the app to inspect the information first and then choose the appropriate support route rather than trying to solve everything through tapping.
Small workflows that make mobile banking less error-prone
One workflow I recommend is the “check, act, verify” sequence. I first confirm that I am looking at the intended account, then review the amount and destination before submitting an action, and finally return to the account activity to make sure the result is visible. It sounds obvious, but mobile interfaces encourage quick taps, and the verification step is what protects against both network confusion and simple input mistakes.
A second useful habit is separating observation from action. If I open the app only to inspect a recent purchase, I do not start changing other settings or moving money at the same time. Keeping the session focused makes it easier to remember what I intended to do and reduces the chance that a poor connection will leave several unfinished tasks competing for my attention.
A third trade-off concerns timing. I avoid beginning important banking work while walking through a busy area, boarding transport, or switching between networks. Those are exactly the moments when attention is divided and connectivity can change. The app is designed for mobile access, but mobile access does not mean every physical context is equally suitable for financial decisions.
I also pay attention to the difference between a visual delay and a genuine account issue. If the app is slow but other online services are also struggling, I investigate the connection first. If the rest of the phone works normally but account information remains unexpectedly unclear, I stop guessing and seek a more reliable way to confirm the situation. That approach prevents the app from becoming a source of unnecessary anxiety.
Who will appreciate it, and who should choose something else
I would recommend TD Bank (US) to an existing TD customer who wants convenient access to everyday banking from a phone. It is particularly suitable for people who check transactions while out, prefer not to depend on a desktop, and are comfortable making careful decisions on a smaller screen. The free price also removes a common barrier for someone deciding whether to use the official mobile option.
I would be more cautious about recommending it to someone whose main goal is comprehensive financial planning across multiple institutions. That person may be better served by a budgeting-focused application or a desktop workflow with more space for comparisons. Likewise, anyone who frequently works in locations with unreliable service should not assume that a mobile banking app will remove the need for another way to confirm important information.
The Everyone age rating makes it broadly approachable, but that does not mean every user will find the workflow equally comfortable. People who are less confident with mobile security, account verification, or reviewing transaction details may prefer using the app alongside a familiar support channel at first. The best experience comes from treating it as a convenient access point, not as permission to rush through financial tasks.
My connectivity verdict
After using TD Bank (US) as a mobile banking tool, I see its strongest quality in the way it brings ordinary TD account tasks into the moments when a computer is not available. Its value rises sharply with a stable connection and a clear purpose. Checking activity, reviewing an account, and handling routine needs feel natural when I give the app time to load and verify the outcome.
Its main limitation is not something I would solve by tapping faster. Connectivity problems can make a finance task feel ambiguous, and a phone’s compact interface leaves less room for careful comparison. That means the app rewards disciplined use: confirm the account, check the details, wait for the response, and verify what happened before repeating an action.
TD Bank, N.A. has produced a practical official option for customers who want everyday banking in a mobile format. I would choose it over a browser for quick TD-specific check-ins, but I would choose a larger-screen workflow or a separate budgeting tool for broader financial organization. The best reason to install it is dependable access to your TD banking routine, not the expectation that a phone can replace every banking channel.
TD Bank (US) FAQ
What is TD Bank, and what can I do with its mobile app?
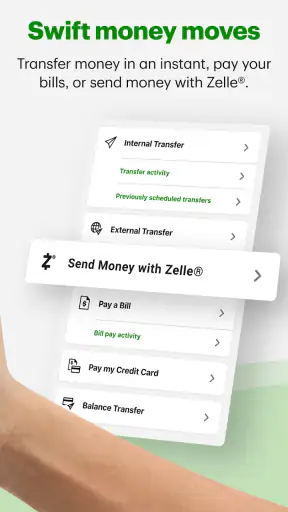
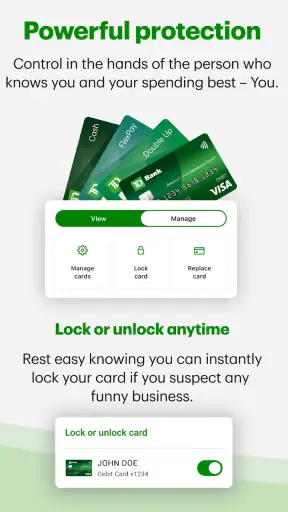
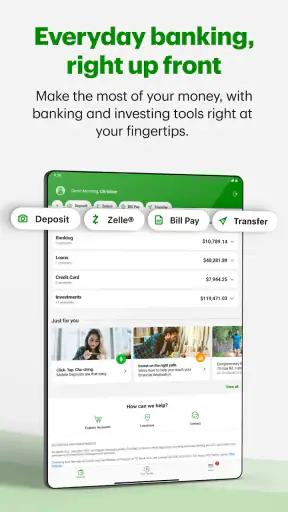
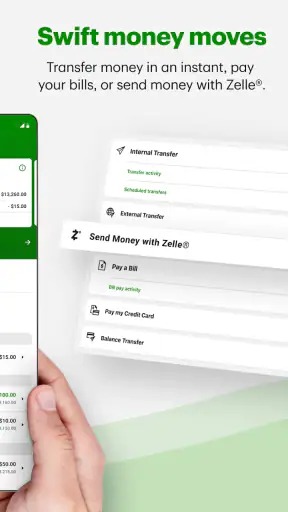
TD Bank is a U.S. financial institution offering checking and savings accounts, credit cards, personal loans, mortgages, and other banking services. Its mobile app lets customers check balances, review transactions, transfer money, pay bills, deposit eligible checks, manage cards, locate branches and ATMs, and contact support. Available features can vary depending on your account type and enrollment status.
Is the TD Bank mobile app safe to use?
The TD Bank app includes security features such as encrypted connections, login protection, alerts, and options for biometric authentication on compatible devices. However, no banking app eliminates every risk. Download it only from the official Google Play Store or Apple App Store, keep your phone and operating system updated, avoid public Wi-Fi for sensitive activity, and never share your password, verification codes, or security answers.
Can I deposit checks using the TD Bank app?
Eligible TD Bank customers can generally deposit checks through the app by photographing the front and endorsed back of the check, entering the amount, and selecting the account. The images must be clear and meet the app’s requirements. Deposit limits, availability times, holds, and eligibility may apply. Keep the original check safely until the deposit is fully processed, then follow TD Bank’s retention guidance.
Does TD Bank charge fees for using its mobile banking app?
Downloading or using the TD Bank mobile app may not involve a separate app access fee, but normal account, transaction, ATM, overdraft, wire transfer, or service charges can still apply. Your mobile carrier may also charge data or messaging fees. Fees and account requirements depend on the product you have, so review the current TD Bank fee schedule and account terms before using specific services.
What should I do if I cannot log in or notice suspicious activity?
If you cannot access your account, check your internet connection, confirm that the app is updated, and use TD Bank’s official password or username recovery options. Do not repeatedly guess credentials or use links from suspicious messages. If you see an unfamiliar transaction, receive an unexpected verification request, or believe your account is compromised, contact TD Bank immediately through the official app, website, or phone number.











